Does it come back today?
The VWAP is the average price of the day. When price is far from it, the question is whether it returns. This tool shows how often it did in the past, in the same situation. It gives odds, not a signal.
Price two sigma away from the VWAP, and the same question every time: does it come back today, or is this a trend day? For years I answered it by feel.
VWAP bands tell you where price is. I wanted to know what that has meant in the past. Algorex VWAP Odds reads three things for the current bar: the New York time of day, the distance from the session VWAP in sigmas, and the freshness, meaning the minutes since price last touched the VWAP. For exactly this situation it shows the odds of a return within two hours and before the session ends, the average time to return, and the heat: how far price typically runs further away first.
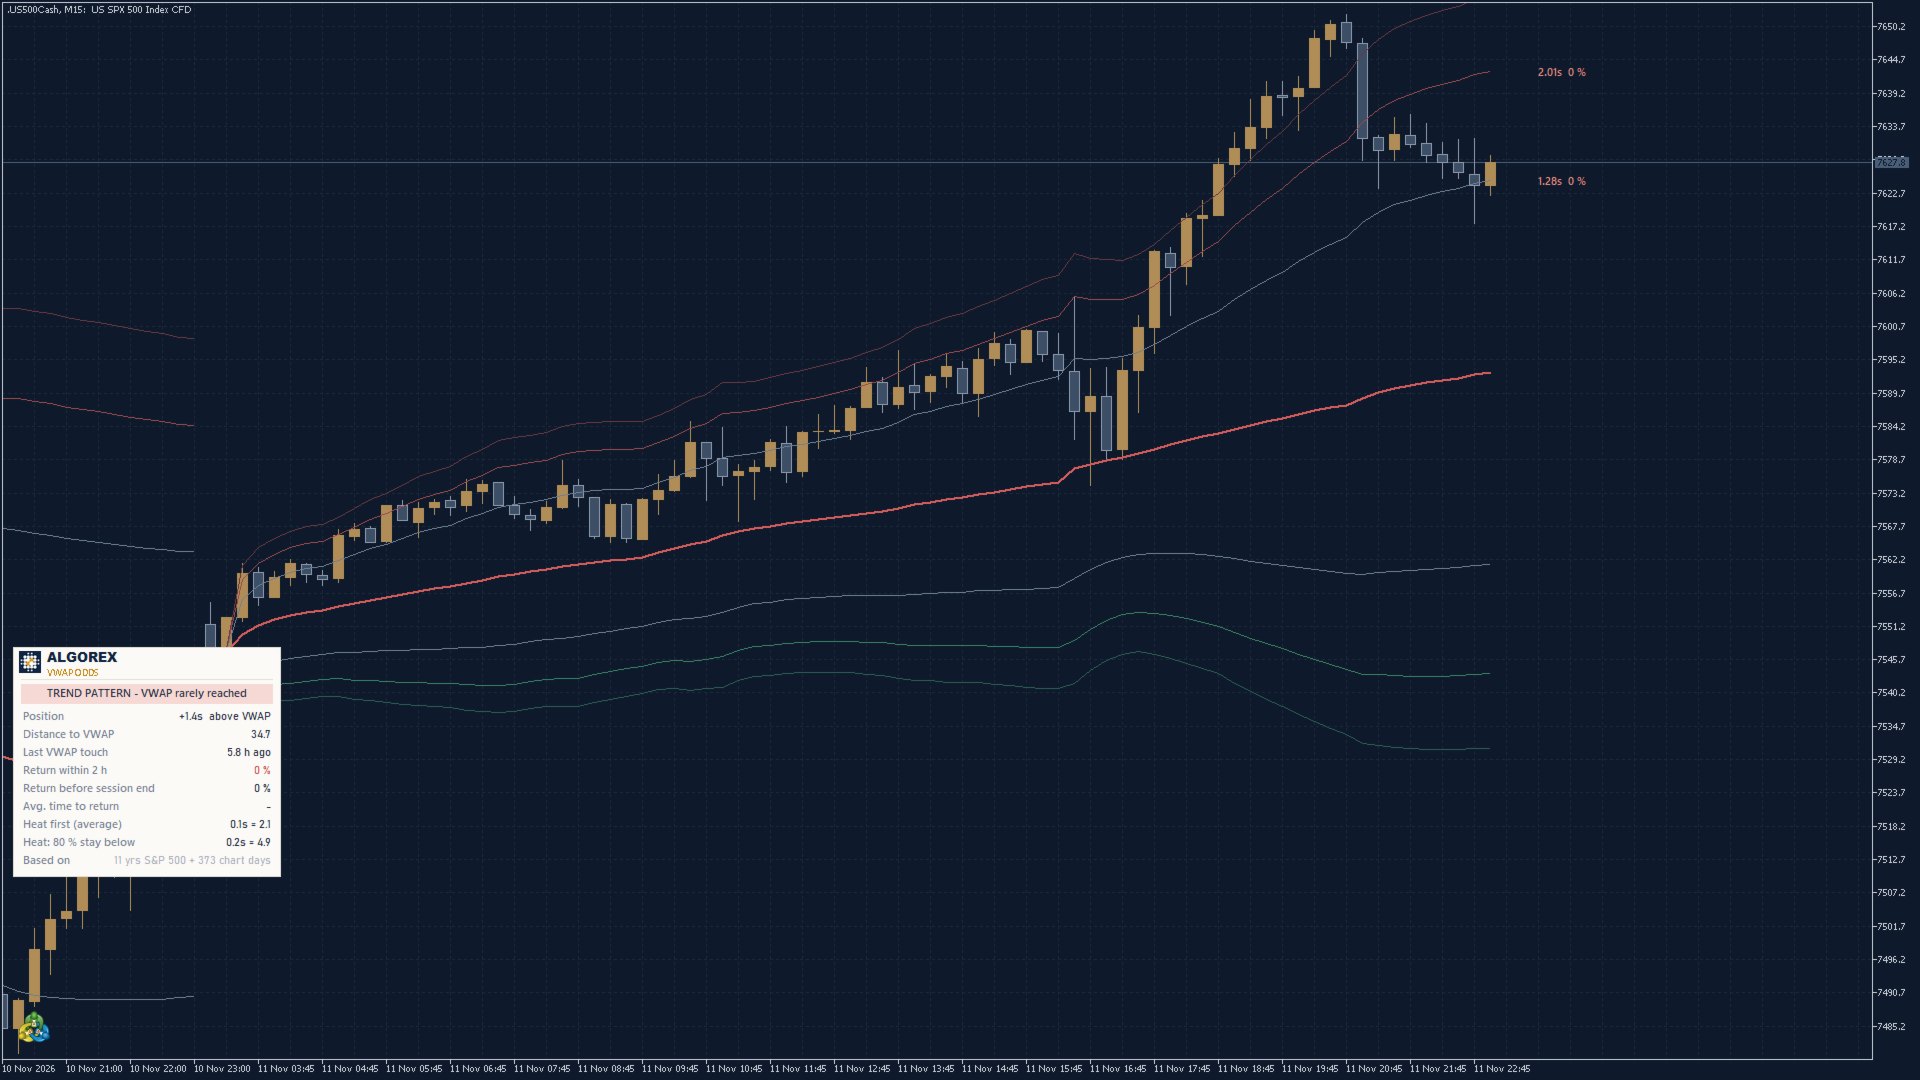
The statistics are built in: tables from 5-minute data from 2015 to 2026 for Nasdaq 100, S&P 500 and gold. On top the tool learns from the chart it is on and blends both.
Freshness matters most. Nasdaq around noon, two sigma from the VWAP: 49 % return within two hours when price left the VWAP minutes ago, 7 % when it has been away for more than three hours.
It is a context tool, not a signal. In the same data a blind fade back to the VWAP averaged zero. Use the odds to judge whether the VWAP is a realistic target, how much heat to expect, and whether the day behaves like a trend day. Past frequencies are no guarantee of future results.
Free for TradingView, MetaTrader 5 and MetaTrader 4.